An incentive exception approval workflow keeps audits short.
October 23, 2026
Puneet Gupta
Puneet Gupta
Key Insights
In the Alexander Group's 2025-26 survey, 65% of firms said they need to improve the governance of their sales incentives. In my conversations with finance controllers, that gap usually has a name: the exception approved on a call and applied in a spreadsheet the week before payout.
Exceptions are often right for the business. A split agreed late, a waiver for a territory hit by floods, a guarantee for a new joiner. The problem is the record. When an auditor asks why one payee received more than the plan allowed, the answer sits in someone's inbox, or with someone who has since left.
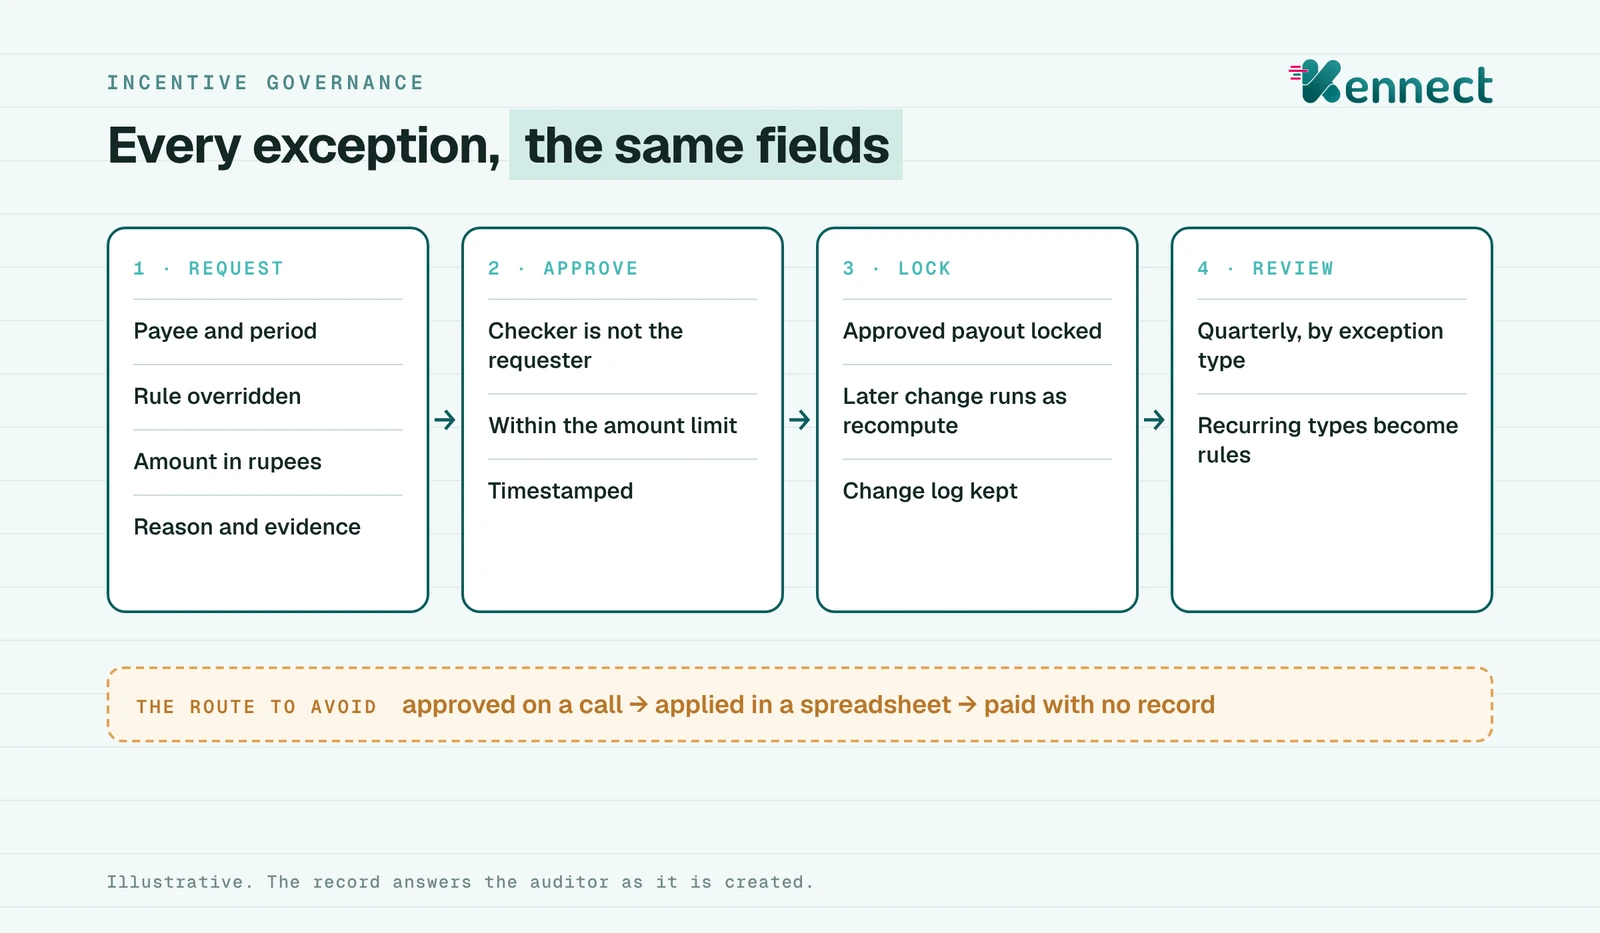
An incentive exception approval workflow fixes that by giving every exception the same fields: requester, rule overridden, amount, reason, evidence, approver and date. Approval limits by amount, separate maker and checker roles, and locked payouts turn the record into a control the auditor can test under Section 143(3)(i).
A question worth asking the finance controller this week: how many exceptions were approved in the previous quarter, and could each one be shown with its approver?
Sources: Alexander Group, 2025-26 Sales Compensation Trends Survey research briefing, hundreds of companies across 11 industries · WorldatWork Workspan Daily, Governance and Operations Are Foundational to Sales Comp Success, 16 July 2026 · figures are survey findings and one case study
Two in three firms want stronger incentive governance, and exceptions are where that governance is tested first.
What counts as an incentive exception
An exception is any payout decision the plan rules did not make on their own. In many sales teams, exceptions fall into eight types.
A manual adjustment to a calculated payout.
An override of a slab, target or gate for one payee.
Credit moved to a different rep or period after the close.
A waiver of a qualifying condition, such as attendance or a ratio gate.
A guaranteed payout for a new joiner.
A recovery reduced or waived.
Each one can be right for the business. Each one also moves money outside the approved rules, which is why it needs a record.
An exception is a payout decision made outside the plan rules, and every one of them needs a reason, an approver and a date.
Why exceptions become an audit question in India
Under Section 143(3)(i) of the Companies Act 2013, the auditor reports on whether the company has adequate internal financial controls with reference to financial statements, and whether those controls operate effectively. For listed companies, Section 134(5)(e) requires directors to state that internal financial controls are in place and operating effectively.
The Act defines internal financial controls to include the prevention and detection of frauds and errors, and the accuracy and completeness of accounting records. An exception approved on a call, applied in a spreadsheet and paid with the rest of the payout leaves nothing for the auditor to test.
Some private companies below set turnover and borrowing limits are exempt from the 143(3)(i) report. The discipline still protects the incentive budget.
Sources: Companies Act 2013, Section 143(3)(i) as amended by the Companies (Amendment) Act 2017, and Section 134(5)(e) with its Explanation · ICAI Guidance Note on Audit of Internal Financial Controls Over Financial Reporting · this post is not legal advice
An exception without a record is a control the auditor cannot test, and a payout the company cannot defend.
What an incentive exception approval workflow should record
A workflow is the set of fields every exception carries from request to payout. The auditor asks for the same fields, so the record answers the audit as it is created.
Fields an incentive exception approval workflow should record, and why the auditor asks for each
Field
What it holds
Why the auditor asks
Requester
Who asked for the exception
Shows who initiated the change
Payee and period
Whose payout, for which close
Ties the exception to one payout
Rule overridden
The plan clause, slab or gate set aside
Shows what the approved plan would have paid
Amount
The change in rupees
Lets the auditor test against approval limits
Reason and evidence
Why, with the supporting document attached
Shows the decision had a basis
Approver
Who approved, separate from the requester
Shows maker and checker were different people
Timestamp and expiry
When it was approved, and whether it repeats
Shows the exception did not become a standing rule by default
Illustrative. Every exception carries the same fields from request to locked payout.
When the exception record holds requester, rule, amount, reason, approver and date, the audit trail builds itself.
How to set up an incentive exception approval workflow
Six steps put a workflow in place before the next close.
Define exceptions in the plan document. List the eight types and state which ones are allowed.
Set approval limits by amount and role. A regional manager approves small adjustments, while finance and the sales head approve larger ones. In SalesGlobe's 2026 research, 52% of companies had a formal mega-deal policy.
Separate maker and checker. The person who requests an exception never approves it.
Require a reason and evidence. No exception moves without both.
Lock approved payouts. A change after approval runs as a recompute with its own reason, inside a window the plan sets.
Review exceptions every quarter, by type. An exception that recurs is a rule waiting to be written, the same way a mid-year incentive plan change needs a dated version.
Count the previous quarter's exceptions by type. The three largest types are the first three rules to write into the plan.
Limits, separated roles, required evidence and locked payouts turn an exception from a favor into a control.
How Kennect handles incentive exceptions
In the finance teams we work with, the exception log usually lives in email. So we keep every exception inside the payout record it changes.
Approvals and locks. Manual adjustments go for approval before they reach a payout, and approved payouts are locked. Scheme changes pass maker-checker approval before any payout uses the revised version. Admins set how far back a recompute can reach.
Audit trail. Every edit sits in a change log with who made it and when. Plans are held as dated versions. Any payout drills down to the data behind it, and the record exports for the auditor.
AI today. Every payout traces back to the plan and KPI behind it, and tracing to the underlying data follows by the end of December 2026. AI-assisted query resolution answers many payee queries before they become exceptions.
AI next. End-to-end exception handling, expected between January and March 2027, will let AI flag a payout exception and carry it through to resolution. AI root-cause analysis and validations, with timing to be confirmed, will check data, calculations and payouts before release.
In one deployment at a mid-sized Indian pharma company with more than 1,000 medical representatives, the time from period close to payout fell to 5 days, against 2 to 3 months before.
Source: Kennect claim register · anonymized mid-sized Indian pharma deployment, 1,000+ medical representatives · close to payout before and after go-live
Exceptions recorded inside the payout, with approvals and locks, give finance a trail it can sign and an auditor a control to test.
What this means before your next audit
Exceptions will keep happening, because markets move faster than plan documents. A company that records each one with a reason, an approver and a date can show the auditor every rupee paid outside the rules, and why.
Every exception recorded inside the payout, with its reason and approver, is a control the auditor can test.
65% of firms say incentive governance needs work. An approval workflow with limits, separated roles and locked payouts closes that gap before the audit.
See how Kennect gives finance an audit trail behind every payout.