At one Indian pharma company we work with, payout queries fell by 80%. It has more than 1,000 medical representatives, and the change came once every rep could read a statement that showed how each number was built.
The queries had a cause that surveys describe well. In a 2025 survey of more than 200 incentive leaders, 66% said their company had overpaid or underpaid commissions in the past year. In a 2026 survey, 74% of reps said they do not trust how their pay is calculated. So reps keep their own spreadsheet of orders, slabs and deductions, and distributors keep their own register of scheme claims. That second ledger is a shadow account.
The cost lands on the company: incentive team hours, selling time lost in the final week of the month, attrition and slow claims. Shadow accounts fade when the statement shows the orders behind each number, the slab reached, each adjustment with its reason and the payout status, while the month is still running.
A question worth asking at the next leadership review: if a rep asked why the previous month's payout changed, how many days would the answer take?
Read together, the two numbers describe one gap from both ends. The company cannot be sure its payouts are right, and the people being paid cannot check them. So the field checks every number itself.
Sources: CaptivateIQ, State of Incentive Compensation Management Report, press release of 6 May 2025, more than 200 US B2B incentive leaders · Salesforce, Trends in Sales Compensation Report 2026, anonymous survey of 500 US sales professionals, August to September 2025
When the company's own payout record cannot answer the field's questions, the field builds a record of its own.
What a shadow account is
A shadow account is a rep's own record of what they believe they have earned. It sits beside the company's payout statement and is kept by the rep, for the rep.
In an Indian field force it takes many forms. A spreadsheet of invoices and slabs. A notebook with the month's doctor calls or dealer orders. Screenshots of the SFA dashboard saved on a phone. A running total in a chat with a colleague in the next territory.
Distributors and stockists keep one too. Theirs is a register of scheme claims and expected credit notes, matched against the company's ledger before anyone signs a balance confirmation.
A shadow account is the field's audit of the company's payout, run every month at the field's own cost.
What shadow accounts cost the company
A shadow account looks like a private habit. Its cost lands on the company's own books, in six places.
Payout accuracy
Every shadow ledger is an independent check on the payout. An underpayment found by a rep becomes a grievance. An overpayment found by the company becomes a recovery, and a recovery from a field force becomes a dispute. Queries that recur on the same rule are one of the commission calculation errors that repeat every cycle.
Management hours
A rep whose ledger disagrees with the statement raises a query. The manager forwards it, and the incentive analyst rebuilds the calculation to answer it. In the sales teams we speak with, one query can take a senior member of the incentive team a day to answer.
Selling capacity
Salesforce's State of Sales research found reps spend 70% of their time on non-selling tasks. A shadow ledger adds to that share. It peaks in the final week of the month, when selling time decides which slab the month closes on.
A distributor who passes a scheme discount to retailers funds it from its own margin until the credit note arrives, and checks every line of it. Since 1 October 2025, amended Section 34(2) of the CGST Act lets a supplier reduce its output tax on a credit note once the distributor has reversed the matching input tax credit. An unreconciled claim is now a tax line the company cannot close on its own.
Data exposure
A shadow ledger often holds more than one person's numbers. Team payout sheets, colleagues' targets and screenshots of internal reports end up on personal phones. India's DPDP Rules apply security safeguard duties to that data from 13 May 2027.
Sources: Salesforce, State of Sales, sixth edition, 5,500 sales professionals, 2024 · Gartner, survey of 3,523 employees, press release of 28 November 2022, figures cover pay in general · CGST Act Section 34(2) as amended from 1 October 2025; this post is not tax advice
The field pays for a shadow account in evenings. The company pays in queries, selling time, attrition and claims that will not close.
Why reps and distributors keep a second ledger
Reps rarely start a shadow account out of suspicion. They start one after a payout surprised them. Each cause points at a process the company owns.
Causes of shadow accounts, and what each tells leadership
What the field tracks
Why they track it
What it tells leadership
The fix
Earnings during the month
The statement arrives weeks after the work
The payout cannot be steered during the period
Show earnings as the month runs
Orders and the cut-off date
A deal booked on the 31st is missing
The statement shows totals without the rows behind them
Publish the cut-off and the deals each statement included
Credit on shared deals
A shared deal pays less than expected
Split rules sit outside the record
Show the credit share on each deal
Deductions and arrears
A recovery lands as one changed total
Adjustments are made by hand, without a reason on record
Show each adjustment as a labeled line
The plan in force
A slab or target moved mid-period
Plans live as circulars without dated versions
Publish dated plan versions with a worked example
Scheme claims
A credit note arrives weeks after the scheme closes
Claims are settled from the distributor's own sheet
Calculate each claim from source data inside the period
A payout the field cannot read is also a payout leadership cannot steer. Both problems close with one shared record.
What an incentive statement needs to retire the shadow account
A rep stops keeping a second ledger when the statement answers the questions the ledger was built to answer. Six elements do that.
The period and the plan version. Which close the statement covers, and which dated plan calculated it.
Each measure with its target, achievement and slab. The rep sees where they landed and why that slab applies.
The deals behind each number. The invoices, orders or policies counted, with dates, so a missing deal is visible at once.
Each adjustment as a labeled line. An arrear or recovery shows the period it belongs to and the reason.
The status of the payout. Calculated, approved, in process or paid.
A way to query a line. The rep raises a question against the number they doubt, without sharing a sheet.
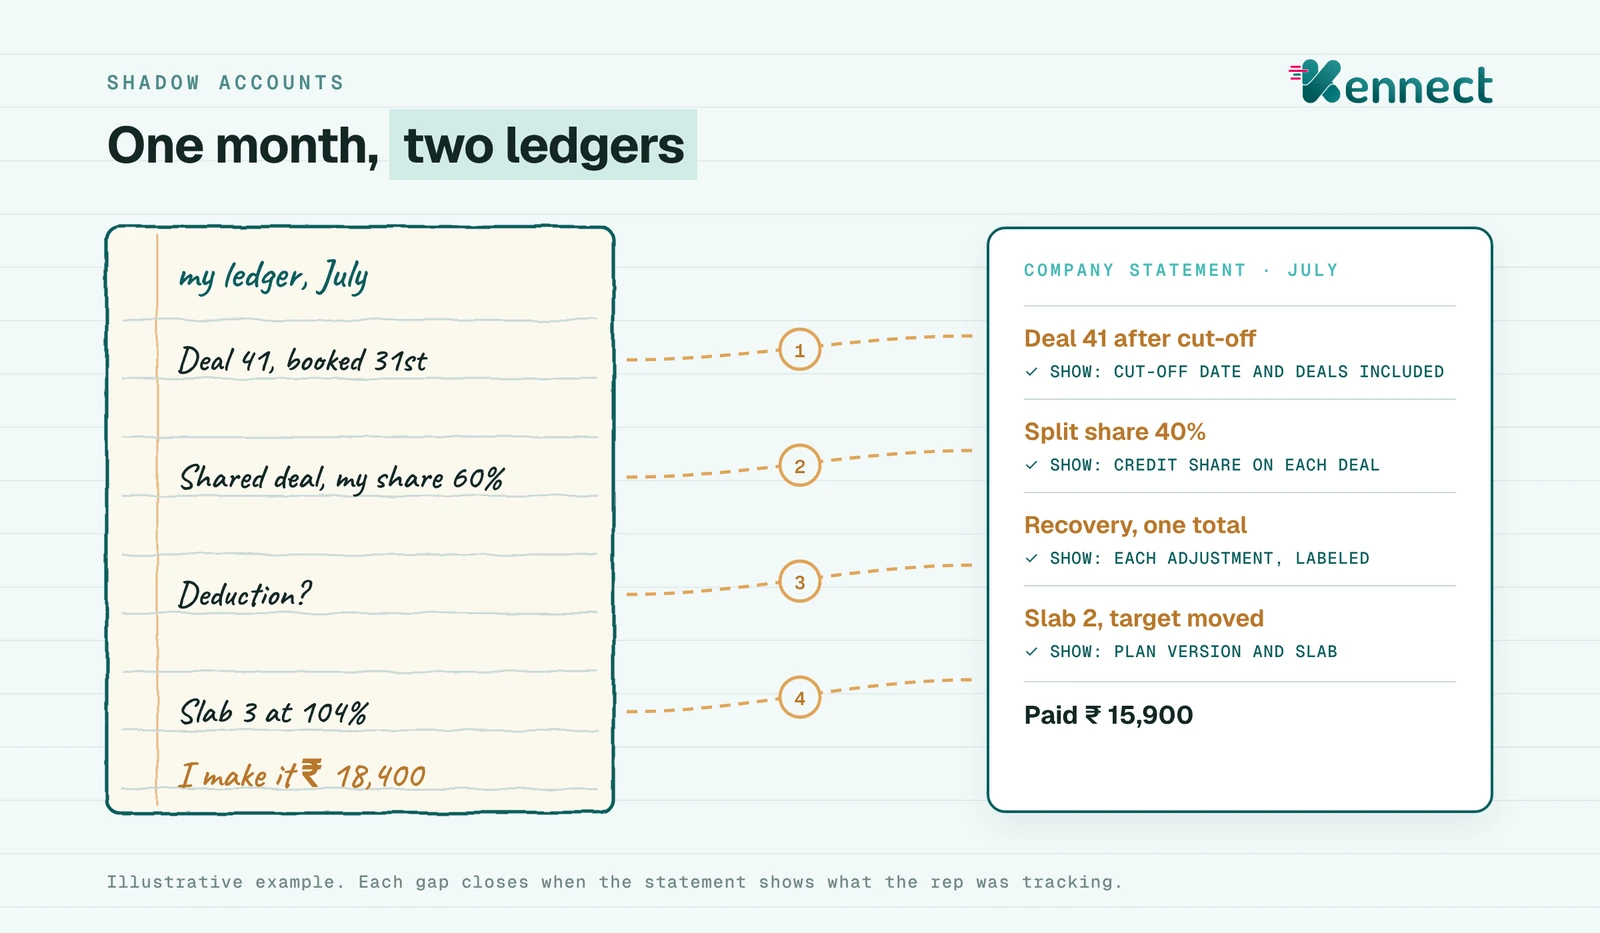
One month, two ledgers. Each gap closes when the statement shows what the rep was tracking.
The statement also has to arrive while it is still useful. A rep who can see earnings during the month can act on the gap to the next slab. Leadership gets the same benefit: an incentive budget it can read while the period is still open.
A statement that shows the deals, the slab, the adjustments and the status answers every question a shadow ledger was built to ask.
Five steps to retire shadow accounts
Sales operations can remove the reasons for a second ledger in five steps.
Publish earnings during the month, refreshed as data arrives, as well as the final statement.
Publish the data cut-off for each close, and show which deals each statement included.
Write each plan in plain language, with a worked example in rupees for each role, and date every version.
Show every adjustment as a labeled line with its period and reason.
Give reps one place to raise a query against a line, and report queries by cause to leadership each month.
Ownership matters as much as the steps. Settle who owns a change to sales incentives and who answers a rep's query, so a question reaches someone who can resolve it.
Count the queries that arrive in the first week after each payout, by cause. The count shows which part of the statement reps still cannot see, and what each cause costs in team hours.
When the statement arrives on time, explains itself and can be queried line by line, the second ledger stops being worth the effort.
How Kennect helps reps see their payout
In the sales teams we work with, many payout queries come from reps who cannot see how a number was built. So we show reps the same calculation the company pays from.
In the Kennect app, each rep sees target, achievement and current earning on every parameter of the plan, for the current period and past ones. They see the slab reached and can simulate what further business would earn. Payout status shows whether an amount is in process, approved or paid. If a past period is recomputed, the difference from the earlier payout is visible with its reason. A rep who doubts a number raises a query in the app, with a description and an attachment.
Finance keeps a change log and approval record behind every payout. Sales leadership sees team performance and earnings in one view. One deployment covers a mid-sized Indian pharma company with more than 1,000 medical representatives. There, queries per cycle fell by 80%, and the time from period close to payout fell to 5 days, against 2 to 3 months before.
Source: Kennect claim register · anonymized mid-sized Indian pharma deployment, 1,000+ medical representatives · queries per cycle and close to payout, before and after go-live
One statement, built from the same calculation the company pays from, gives the rep nothing left to reconstruct and gives leadership a payout it can stand behind.
What this means for the next leadership review
Shadow accounts will keep forming wherever the payout is harder to read than to rebuild. Each one marks a question the company's record cannot yet answer. A company that closes those gaps spends fewer hours on queries, pays more accurately and keeps more of its field.
One statement, built from the same calculation the company pays from, gives the rep nothing left to reconstruct.
66% of companies mispaid commissions in a year, and 74% of reps distrust how their pay is calculated. A statement that shows the deals, slabs and adjustments, during the month, closes both gaps.
See how Kennect shows every rep the number the company pays from.